You Served. Your Medicare Choices Deserve Clarity.
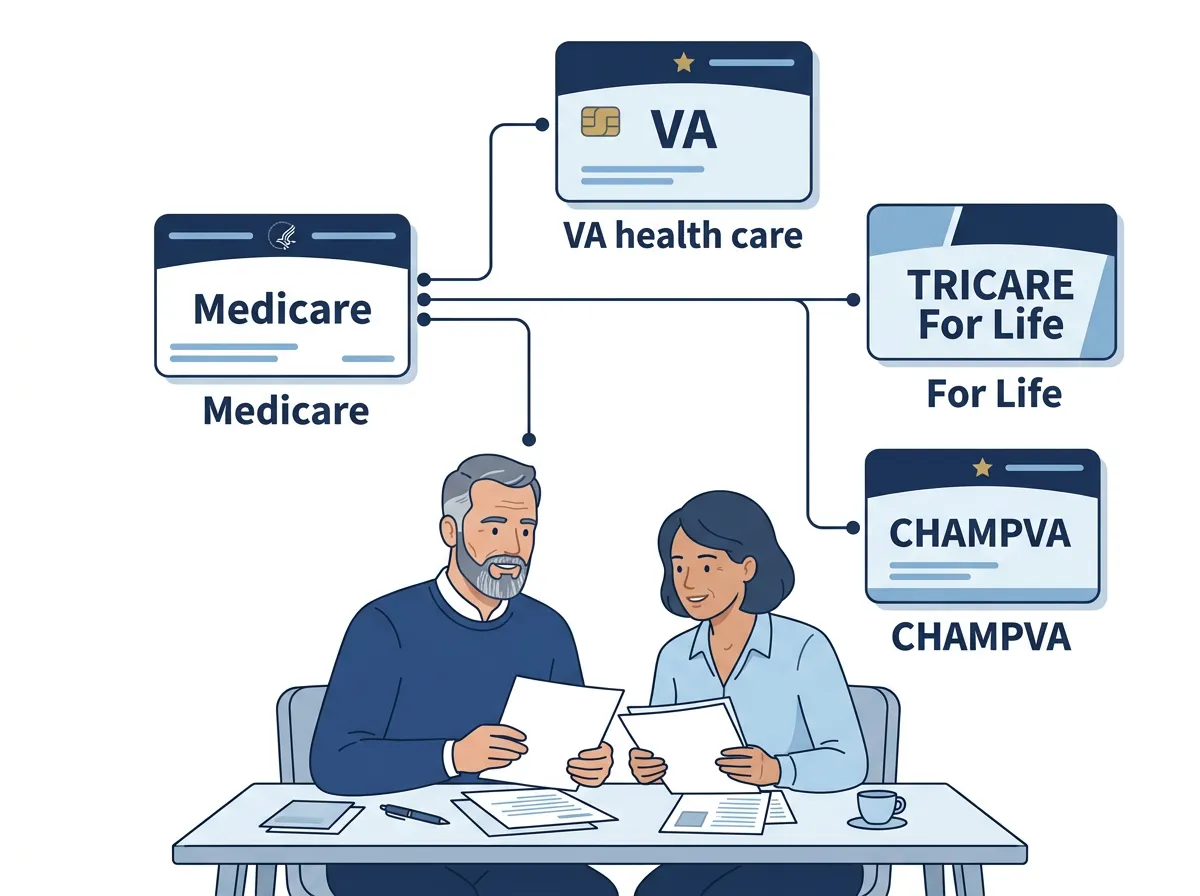
Understand how VA health care, TRICARE For Life, CHAMPVA, and Medicare may work together.
MILITARY & VETERAN HEALTH COVERAGE
Compare essential healthcare programs designed for service members, military retirees, and eligible dependents to make informed decisions about your medical coverage.
VA Health Care
Comprehensive medical benefits administered directly through the Department of Veterans Affairs. Coverage includes preventive exams, inpatient hospitalization, specialty clinics, and prescriptions tailored for discharged military personnel based on Priority Group assignments.
TRICARE For Life
Medicare wraparound coverage for military retirees and family members eligible for TRICARE. Delivers secondary payment coordination for Medicare Part A and Part B deductibles, coinsurance, and global healthcare expenses without enrollment fees.
CHAMPVA
Civilian Health and Medical Program of the VA, offering comprehensive fee-shared health insurance for spouses, surviving spouses, and dependent children of veterans rated permanently and totally disabled from service-connected conditions.
VETERANS & MILITARY HEALTHCARE COMPARISON
Understanding How Military Benefits Coordinate With Medicare
Navigating medical coverage as a veteran or military retiree requires understanding distinct rules. VA Health Care, TRICARE For Life, and CHAMPVA do not function identically alongside Medicare Part A, Part B, and Medicare Advantage. Review how each program coordinates to avoid unexpected out-of-pocket expenses and lifelong late-enrollment penalties.
- TRICARE For Life mandates Medicare Part B enrollment to maintain coverage past age 65.
- VA Health Care does not bill Medicare: maintaining both protects your civilian care options.
- CHAMPVA operates as secondary coverage to Original Medicare for eligible spouses and dependents.
Updated for 2026 CMS & Department of Veterans Affairs guidelines.
Direct Comparison: Veterans Healthcare vs. Medicare Programs
Scroll horizontally to compare all 5 programs| Plan Dimension | VA Health Care | TRICARE For Life | CHAMPVA | Original Medicare | Medicare Advantage |
|---|---|---|---|---|---|
| Target Eligibility | Enrolled military veterans meeting active service & priority group rules. | Military retirees & family members entitled to Part A & enrolled in Part B. | Spouses/dependents of veterans rated 100% permanently service-disabled. | U.S. citizens & permanent residents age 65+, or qualifying disability. | Individuals enrolled in Part A & B residing in plan contract service area. |
| Provider Network | VA facilities only. Community Care requires prior written authorization. | Any provider accepting Medicare nationwide plus military clinics (space-available). | Any licensed medical provider accepting Medicare or CHAMPVA allowable rates. | Over 90% of civilian doctors & hospitals nationwide accepting assignment. | Strict regional HMO/PPO networks; out-of-network care typically restricted. |
| Monthly Premium | $0 Premium $0 monthly fee for veteran enrollment. |
$0 TFL Fee Requires standard Medicare Part B premium. |
$0 Premium Requires Part B premium upon turning 65. |
Standard Part B Part A usually $0; Part B has standard premium. |
Varies ($0-$80+) Often $0 premium beyond Medicare Part B. |
| Prescription Drugs | VA formulary via VA mail order & pharmacies. Copays tiered by priority group. | TRICARE Pharmacy Program (Express Scripts mail order & commercial retail). | Meds by Mail program with $0 copay or 25% cost-share at retail network. | Requires separate Medicare Part D plan; no Part A/B outpatient drug coverage. | Usually bundled into plan (MAPD); formulary and pharmacy network rules apply. |
| Medicare Coordination | Separate Systems Does not bill Medicare. VA pays VA care; Medicare pays civilian care. |
Wraparound Secondary Medicare pays primary; TFL covers remaining deductibles and coinsurance. |
Secondary Payer Medicare pays primary; CHAMPVA covers remaining cost-shares. |
Primary Foundation Forms the essential primary payer foundation for TFL and CHAMPVA. |
Caution for TFL May complicate TRICARE claims processing and prior authorizations. |
| Key Recommendation | Enroll in Part B as civilian backup in case VA funding or proximity changes. | Must enroll in Part B at 65 to avoid losing all military health benefits. | Must maintain Part B at 65 to preserve secondary CHAMPVA benefits. | Pair with Medigap or military secondary coverage to cover 20% coinsurance. | Carefully verify veteran benefits compatibility before selecting Part C. |
CRITICAL VETERAN HEALTHCARE DIRECTIVE
Before You Make a Medicare Decision
VA benefits provide essential healthcare, but they do not integrate with Medicare automatically. Understanding how both systems interact prevents irreversible penalty fees, out-of-pocket emergency costs, and gaps in specialized treatment.
1. VA Coverage Is Not Creditable for Part B
VA health benefits do not qualify as creditable coverage for Medicare Part B. Delaying Part B enrollment when eligible results in a permanent 10% penalty for every 12 months you waited without qualifying employer coverage.
2. Non-VA Emergency Room Liabilities
VA coverage only pays for civilian emergency room or urgent care visits under strict notification windows and eligibility requirements. Medicare Part A and B eliminate non-VA emergency denial risks wherever you are taken.
3. Immediate Access to Civilian Specialists
Enrolling in Medicare unlocks care from any Medicare-accepting civilian specialist or hospital nationwide. You bypass VA travel constraints and avoid waiting for Community Care Network pre-authorizations.
4. Medication Formulary Differences
The VA national drug formulary is strict and may not cover every prescription prescribed by non-VA physicians. Having commercial Medicare drug options gives you local retail pharmacy access and expanded prescription choices.
5. Protection Against Priority Group Changes
Veterans are assigned to one of eight priority groups subject to congressional budget allocations and income thresholds. Retaining Medicare provides a permanent safety net if VA enrollment rules or your local priority funding shift.
6. Dual-Benefit Advantage & Part B Rebates
Veteran-centric Medicare Advantage plans frequently offer $0 monthly premiums with Part B cash givebacks, comprehensive dental, vision, and hearing benefits - all while keeping your full VA coverage completely intact.
Coordinate Your VA and Medicare Coverage Without Conflict
Every veteran's service rating, household income, and local medical needs are distinct. Speak with an accredited veteran healthcare coordinator to ensure your enrollment dates and options are synchronized properly.
Personalized Medicare Guidance
Independent Medicare Guidance You Can Trust
Navigating Medicare doesn't have to be complicated. As an independent, licensed Medicare insurance agent, I provide personalized guidance to help you understand your coverage choices. Licensed in 37 states!
Whether you're turning 65 or retiring after 65, I'll help you review your Medicare enrollment timeline, compare available coverage options, and make informed decisions based on your healthcare needs, preferred doctors, medications, and budget.
- Personalized Medicare guidance based on your healthcare needs, preferred doctors, prescription medications, and budget.
- Personalized Medicare coverage reviews that consider your preferred doctors, prescription medications, healthcare needs, and budget.
- Guidance through Medicare enrollment periods, including Turning 65 and Special Enrollment Periods for those retiring after age 65.
- Clear, unbiased explanations of Medicare Supplement (Medigap), Medicare Advantage (Part C), and Part D prescription drug coverage options.
TESTIMONIALS
What Client Our Says About Us
I’ve worked with many insurance providers globally, but none have offered such personalized service. Their team truly goes above and beyond.
Exceptional experience from start to finish. They took the time to understand my needs and offered the best solutions tailored to my situation.
I’m impressed by their global reach and professionalism. Their quick responses and reliable support make them my top choice for health coverage.
Frequently Asked Questions
Do veterans need Medicare if they have VA health care?
While VA health care provides comprehensive medical services for service-connected conditions at VA facilities, it does not cover civilian medical providers or private hospitals. Enrolling in Medicare Parts A and B gives you the freedom to receive care outside the VA system, protects against future priority group funding changes, and avoids lifelong late-enrollment penalties.
Can I have VA health care and Medicare Advantage?
Yes. Many veterans combine VA benefits with a Medicare Advantage (Part C) plan. In fact, specialized 'veteran-oriented' Medicare Advantage plans often include Part B premium reduction givebacks, dental, vision, hearing, and gym memberships while allowing you to keep getting your prescription drugs and primary care through the VA.
Does TRICARE For Life require Medicare Part B?
Yes. To maintain TRICARE For Life (TFL) coverage upon turning 65, military retirees and their eligible dependents must be enrolled in both Medicare Part A and Part B. Under TFL, Medicare acts as the primary payer for Medicare-covered services and TRICARE covers virtually all remaining copayments and deductibles.
How does CHAMPVA work with Medicare?
For eligible spouses and dependent children of permanently disabled or deceased veterans, CHAMPVA coordinates directly with Medicare. Upon becoming eligible for Medicare, beneficiaries must enroll in Medicare Parts A and B. Medicare becomes the primary payer, and CHAMPVA functions as secondary payer, minimizing out-of-pocket costs.
Will Medicare pay for services at a VA hospital?
No. Medicare cannot pay for medical treatment received at Veterans Affairs (VA) health facilities, and the VA does not bill Medicare. The two systems remain completely separate: Medicare covers certified civilian providers, while the VA covers care provided within its own network.
Should veterans consider Medicare Supplement insurance?
If you rely on VA health care but do not have TRICARE For Life, a Medicare Supplement (Medigap) plan can provide extensive financial security. It helps pay for Medicare copays and deductibles, allowing you to see any physician or specialist across the nation who accepts Medicare without network limitations.
What happens if I delay Medicare Part B enrollment?
VA health benefits do not qualify as 'creditable coverage' for Medicare Part B. Delaying Part B enrollment without qualifying active employer-sponsored group coverage incurs a cumulative, permanent 10% late penalty for each full 12-month period you were eligible but unenrolled, plus restricted enrollment windows.
Can I use Medicare when traveling outside my local VA health care system?
Yes. Original Medicare is honored by over 90% of doctors and hospitals across all 50 states. Having Medicare ensures that whether traveling, visiting family, or wintering in another state, you have immediate access to emergency and routine medical care without waiting for VA travel authorization.
Your Service Matters. So Does Your Medicare Coverage.
Whether you're approaching age 65, retiring from employment, or already receiving military health benefits, we can help you understand the Medicare coverage options available to you.
As an independent Medicare insurance agent licensed in 37 states, Mark Webb provides personalized guidance to help you navigate enrollment periods, compare Medicare coverage choices, and coordinate VA health care, TRICARE For Life, and CHAMPVA with Medicare.